Home / Condo Insurance

West Chester Condo Insurance: Your association's bad day can become your bill.

Many condo policies carry a small default for loss assessment. A master policy deductible or a shortfall on the whole building can be far bigger. We compare more than one option and close the gap.

HO-6Your Policy, Walls In
3Master Policy Types To Know
OptionsCompared For You
LocalBased in West Chester
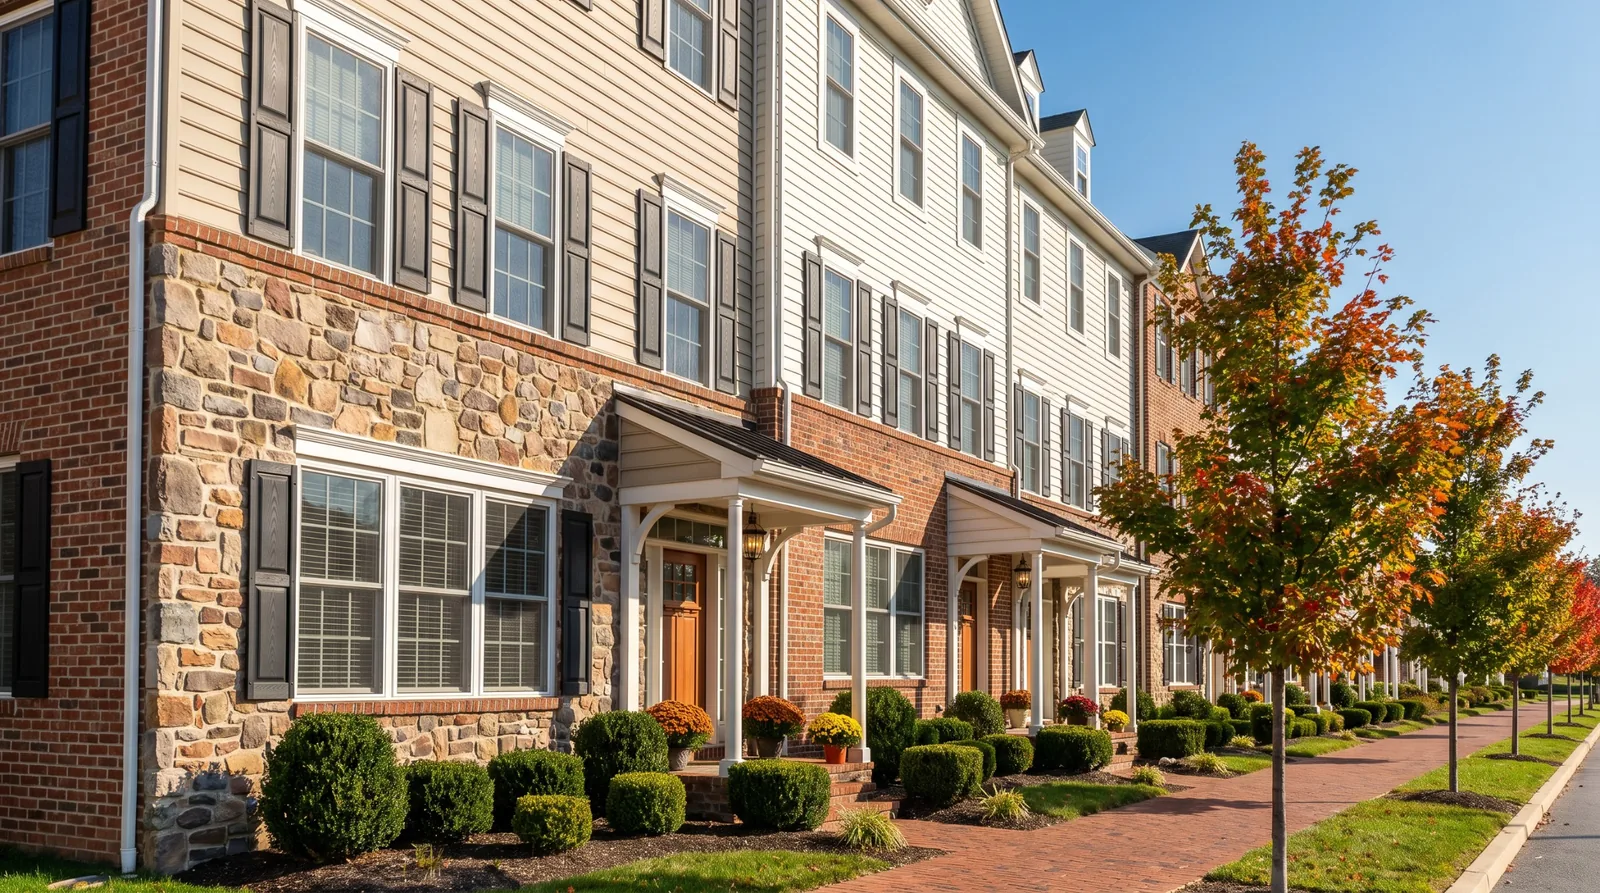
Stone and wood condo buildings with landscaped grounds
The Quick Answer

A condo policy (HO-6) covers your unit from the walls in, your belongings, your liability, loss of use and loss assessment. Your association's master policy covers the building and common areas, and the boundary between the two is set by your declaration and bylaws, not by either policy. Master policies come in three types: bare walls-in, single entity and all-in. The number to watch is what the association can pass on to owners: a large master deductible or a loss that runs past the master policy's limits can become a special assessment, while many HO-6 policies start with a low loss assessment default. In Pennsylvania winters, frozen pipes and ice dams can damage several stacked units at once. Flood needs its own policy for your belongings. The Natelli Agency in West Chester reads the master policy with you and compares Farmers® and other insurance companies. Call (914) 419-8000.

Your policy covers
Walls in, plus assessments
Start with
The master policy declarations page
Biggest gap
Loss assessment vs. the master deductible
Call first
(914) 419-8000
West Chester Condo Insurance, The Short Version

One number on your policy is probably small. Your building's deductible probably isn't.

Condo insurance looks simple. The association insures the building, you insure your stuff, and everyone gets on with life. That story holds up until the building has a serious problem. Around Chester County that's usually water: a pipe that bursts in a January cold snap and runs through several units, an ice dam on a shared roof, or a creek that rises the way the Brandywine did after Ida.

When a loss exceeds the master policy limits, or the master policy has a large deductible that somebody has to pay, the board can levy a special assessment and split the cost among every owner. Now it's your bill, in an amount you didn't choose. Run it once with round numbers: for example, if a loss runs $500,000 past what the master policy pays, and the community has 50 units, that's about $10,000 per owner.

Your HO-6 has a coverage built for exactly this, called loss assessment. The default limit on many policies is small, which against a five- or six-figure shortfall falls well short. Raising it often costs relatively little. One more piece of fine print to ask about: some policies cap the portion of an assessment that comes from the master deductible, no matter how much loss assessment coverage you bought. We check that clause by name.

The second thing nobody tells condo owners: your declaration and bylaws, not your policy, define where the association's responsibility ends and yours begins. Older communities and amended declarations can draw that line in different places. So the right way to insure a condo is to start with the master policy declarations page and the declaration, then build the HO-6 to fit the gap they leave. Then we compare more than one option to find the right fit. Bring the paperwork.
Three master policies. Yours decides what you need.

Ask your association which one your building carries. It's the most useful question a condo owner can ask, and most owners have never asked it.

Master type 1
Bare Walls

Bare Walls-In

Covers the structure and common areas and stops at your studs. Everything inside is yours: drywall, flooring, cabinets, counters, fixtures and appliances. This needs the most dwelling coverage on your HO-6.

Master type 2
As Built

Single Entity

Covers your unit as it was originally built, but not what you've done since. Your renovated kitchen and the floors you replaced are improvements, and improvements are yours. Middle of the road, and the most commonly misunderstood.

Master type 3
All-In

All-Inclusive

Covers fixtures and finishes inside the unit too, leaving you mainly your belongings, your liability and assessments. It costs the association the most and needs the least from you. More common in newer mid-rise and luxury buildings.

The big one
Match It

Loss Assessment

Pays your share when the association levies a special assessment after a covered loss or to meet its master deductible. The default is often small. Match it to the largest deductible on the master policy and a realistic shortfall, and ask whether deductible-driven assessments are capped.

Commonly missed
Your Reno

Improvements & Betterments

The kitchen you redid, the floors you upgraded, the built-ins. Even a generous master policy usually insures the unit as originally built. Your upgrades belong in your dwelling limit, at what they'd cost to redo today.

Core
$300k+

Personal Liability

The guest who falls, and the burst supply line in your unit that soaks the condo below. In stacked buildings, water travels down and finds neighbors on the way. This is the coverage that answers for them.

Winter
Burst Pipes

Water Damage From Inside

Sudden water from a pipe that freezes and bursts is often covered for your interior and belongings, subject to your deductible and reasonable care. A unit left unheated can be excluded. In a Pennsylvania cold snap, one burst line can travel through several floors.

Not covered
Common Areas

The Building Itself

Roof, exterior, hallways, elevators, pool and parking. That's the master policy's job, funded by your dues. Your exposure there isn't the repair cost, it's the assessment that follows when the master policy falls short.

Not covered
Upkeep

Maintenance Assessments

An assessment has to come from a peril your policy covers. Resurfacing the pool, replacing a worn-out roof or refilling an underfunded reserve is maintenance, and no policy pays for that. Read the reserve study before you buy. For rising water, your belongings need their own contents flood policy.

Do you know your loss assessment limit?

Almost nobody does, and it's often small. Send us your declarations page and your association's master policy page, and we'll find the gap.

Getting It Right

How to actually insure a condo, in order.

There's a right sequence here, and it doesn't start with your own policy. It starts with two documents you may never have read.

1. Get the master policy declarations page

Ask your property manager or board. Your association carries a master policy on the building, and asking what it says is a routine request.

You're looking for two things. Which type it is: bare walls-in, single entity or all-in. And every deductible, per peril, along with the limits, because the largest deductible on that page is the number most likely to become an assessment with your name on it. If the master deductible is five or six figures, a small loss assessment limit on your policy isn't protection, it's a formality.

2. Read the declaration for the boundary

This is the step people skip and later regret. Your declaration, not either insurance policy, decides who pays for what after a loss. Windows, balconies, patios and plumbing are the usual battlegrounds, and different declarations draw the lines differently. Older buildings and amended declarations can surprise you.

3. Build the HO-6 to fill the actual gap

Now the policy makes sense. Your dwelling limit covers what the master policy doesn't, including your improvements at today's cost. Your personal property reflects what you actually own, with valuables scheduled. Your liability is sized for stacked living, where your burst hose can become a neighbor's ceiling. Your loss of use reflects what a comparable place rents for nearby. Your loss assessment matches the master policy's biggest deductible, with the deductible-assessment cap checked by name. If you're on the ground floor or have a basement, ask about a water backup endorsement for sewer and drain backup. And if you want protection beyond the master policy's liability, an umbrella policy can sit on top of your HO-6 and auto.

4. Plan for Pennsylvania winters inside the unit

Nor'easters and winter storms bring cold snaps, and cold snaps bring frozen pipes and ice dams. The master policy handles the building, but water from a burst pipe in your unit can still land on your HO-6, and on your neighbors. Damage tied to a unit left unheated can be excluded. If you travel in winter, keep the heat on and know where your unit's water shutoff is.

5. Watch what's happening to your association

When a master policy renews with higher deductibles, lower limits, actual cash value roof settlement or narrower terms, that risk doesn't disappear. It moves to the owners, as bigger assessments when something goes wrong. So the year your association's insurance gets worse is the year your loss assessment limit matters most. If your board sends a notice about the master policy, bring it to us and we'll tell you what it did to your exposure. On interpreting the declaration or any dispute with the association, talk to an attorney. We handle the insurance side.

Did your association just change its master policy?

Cuts to the master policy move risk onto owners. If a notice landed in your mailbox, bring it in and we'll show you what changed for you.

Every building is different. So is every policy.

A stacked unit, a townhome, the condo you rent out, the one you just put an offer on. Each one changes the answer.

Bring the master policy page. We'll do the rest.

We'll tell you which type your association carries, what it leaves you and what your HO-6 should actually say, then compare more than one option. Free.

Condo insurance in West Chester. Condos and townhomes across Chester County.

Condo and townhome communities in West Chester, Exton, Downingtown, Malvern, Phoenixville and King of Prussia, and across Chester County and the Main Line. Every association is different. Tell us where the unit is.

West Chester condo insurance questions. Straight answers.

What does condo insurance actually cover?

An HO-6 policy covers your world from the walls in: your unit's interior and improvements, your personal property, your personal liability, loss of use if the unit can't be lived in, and loss assessment, the piece almost everyone under-buys.

It doesn't cover the roof, exterior, hallways, pool or parking. Those belong to the association's master policy, and the line between the two is drawn by your declaration and bylaws, not by either insurance policy.

What's the difference between my HO-6 and the HOA master policy?

The master policy is bought by the association and paid for through your dues. It covers the building and common areas, and sometimes parts of the units. Your HO-6 is your own policy for what the master policy leaves to you, plus your belongings, your liability and your share of assessments.

The two are meant to fit together without gaps or overlap. The only way to know where the seam is: read the master policy declarations page and your declaration, then build the HO-6 around them.

What is loss assessment coverage, and why does everyone say it matters?

When a loss exceeds the master policy limits or triggers a large master deductible, the board can levy a special assessment and divide the bill among all owners. Loss assessment coverage on your HO-6 pays your share.

The catch: many policies start with a small default limit, while a master deductible or a loss that runs past the master policy's limits can be far larger once it's split across the owners. Raising the limit often costs relatively little, and it's one of the most useful lines on the policy.

What are the three types of HOA master policy?

Bare walls-in covers the structure but nothing inside your unit. Single entity covers the unit as originally built, but not your upgrades.

All-in covers interior fixtures and finishes too. Which one your building carries decides how much dwelling coverage you personally need. Declarations vary, and older communities and amended declarations can surprise you, so read yours.

Who pays the master policy's deductible after a loss?

Often, the owners do. Depending on your declaration and bylaws, the association may be able to pass the master policy's deductible on to owners as an assessment, and a large deductible split across a community can become a real bill.

Here's the fine print that matters: some HO-6 policies cap the portion of an assessment that comes from a master policy deductible, regardless of your overall loss assessment limit. Ask that question by name before you need it.

Does condo insurance cover burst pipes and ice dams?

Often, for the parts that are yours. Sudden water damage from a pipe that freezes and bursts, or from an ice dam forcing meltwater into the building, is commonly covered, subject to your deductible and the policy's conditions. Damage tied to neglect, or to a unit left unheated, can be limited or excluded.

In a stacked building, one burst line in a cold snap can damage several units at once. The master policy handles the building, but your interior, belongings and liability to the neighbors below can still land on your HO-6. Keep the heat on when you travel and know where your unit's water shutoff is.

Does condo insurance cover flooding?

No HO-6 covers rising water. The association can insure the building against flood with its own policy, and if the building is underinsured, the shortfall can come back to owners as an assessment.

Your belongings need a separate contents flood policy, which may be available through the NFIP or a private flood insurer. NFIP policies usually have a 30-day waiting period. The remnants of Hurricane Ida flooded homes across southeastern Pennsylvania in 2021, many outside high-risk zones, so for communities near the Brandywine, Chester Creek or the Schuylkill, we check both layers.

Who pays when water damage crosses between units?

It's the most common dispute in condo living, and it's fact-specific. It turns on where the water came from, who owns the plumbing that failed, and negligence.

Roughly, water from association-owned lines is the association's responsibility for the structure, though your interior may still fall to your HO-6 depending on the master policy type. Water from a pipe inside your unit is yours, and if it soaks the units below, your liability coverage answers for their damage.

Do I have to carry condo insurance?

If you have a mortgage, your lender almost certainly requires it.

And often your declaration or bylaws do too, which can require unit owners to carry an HO-6 with minimum limits. Even without a requirement, going without leaves your interior, belongings, liability and share of any assessment uncovered.

How much dwelling coverage do I need on a condo?

It depends on the master policy type. Under bare walls-in, you insure everything from the studs in: flooring, cabinets, fixtures and interior walls. That's a substantial number.

Under single entity, you insure your improvements and betterments at what they'd cost to redo today. Under all-in, you need relatively little dwelling coverage. Start with the master policy declarations page, then build the HO-6 to fit the gap.

What's the difference between condo insurance and renters insurance?

Ownership. A renters policy (HO-4) covers belongings and liability but no part of the structure, because you own none of it.

A condo policy (HO-6) adds dwelling coverage for the interior you do own, plus loss assessment for your share of the association's shortfalls. If you rent out a condo you own, you need a landlord policy instead, and your tenant needs renters insurance.

What should I check before buying a condo?

Three documents before you fall in love: the master policy declarations page (which type, and every deductible), the declaration and bylaws (where the association's responsibility ends and yours begins, and any insurance requirements on owners), and the reserve study (an underfunded association is a future assessment with your name on it, and no policy covers maintenance).

We read the insurance pieces with buyers all the time, at no charge.

My HOA just changed its master policy. What should I do?

Bring us the notice.

When a master policy shrinks, with a higher deductible, lower limits or a switch from all-in to bare walls, the risk doesn't disappear. It moves to the owners as bigger assessments and bigger personal coverage needs. A few minutes with the new declarations page tells you what changed for you and what your HO-6 needs to absorb it.

Why work with a local agent for condo insurance?

You get a real person and more than one option. We start with Farmers® and can look at other insurance companies when that's the better fit. Loss assessment limits, deductible-assessment caps and water damage terms vary from policy to policy, and those differences matter more than the price alone.

Louis Natelli and his team are local to West Chester and work with condo and townhome owners across Chester County. Call (914) 419-8000 and bring your master policy page.

Still have questions? Call (914) 419-8000. We'll give you a straight answer.

Find the gap before the assessment does.
Free, local and in plain English.

Bring your declarations page and your association's master policy page. We'll show you where your coverage ends and compare what it costs to close the gap.