
 Most Popular
Pennsylvania coverage,
shopped for
you
A local agency in West Chester that compares your options for home, auto, life and business insurance, so you don't have to. That's The Natelli Agency.
Get My Free QuoteLocalagency
One callmore than one option
PAWest Chester office
6+ peopleon our team
Local to West Chester, PA
Personal service, close to home.
We work for you, not a call center. Louis Natelli and his team look at more than one option for your coverage, explain each one in plain English, and stay with you from the first policy through every renewal. You work with the same local team every time.
1
Local agent who knows your file
6+
People on our team
PA
Office in West Chester
1
Business day to hear back
The Natelli Agency helps protect the life you're building.
We shop. You choose. More than one option for your coverage, compared for you.
Talk to a real person. Louis and his team, not an 800-number queue.
A free review, every year. As your needs and the market change, your coverage keeps up.
Help when you file a claim. Report it any time, then call us and we'll walk you through it.
Landlords welcome. Coverage for the rental homes you own around Chester County.
Local business owners. Business coverage for West Chester and Chester County companies.
Ready for winter. Frozen pipes, ice dams and water backup coverage reviewed before the first cold snap.
Bundle home + auto. One agency, one review, and bundling may lower what you pay.
Most Popular

 Bundle & Review
 Condos & Townhomes
 Apartments & Rentals
 Rental Property Owners
 For Business Owners
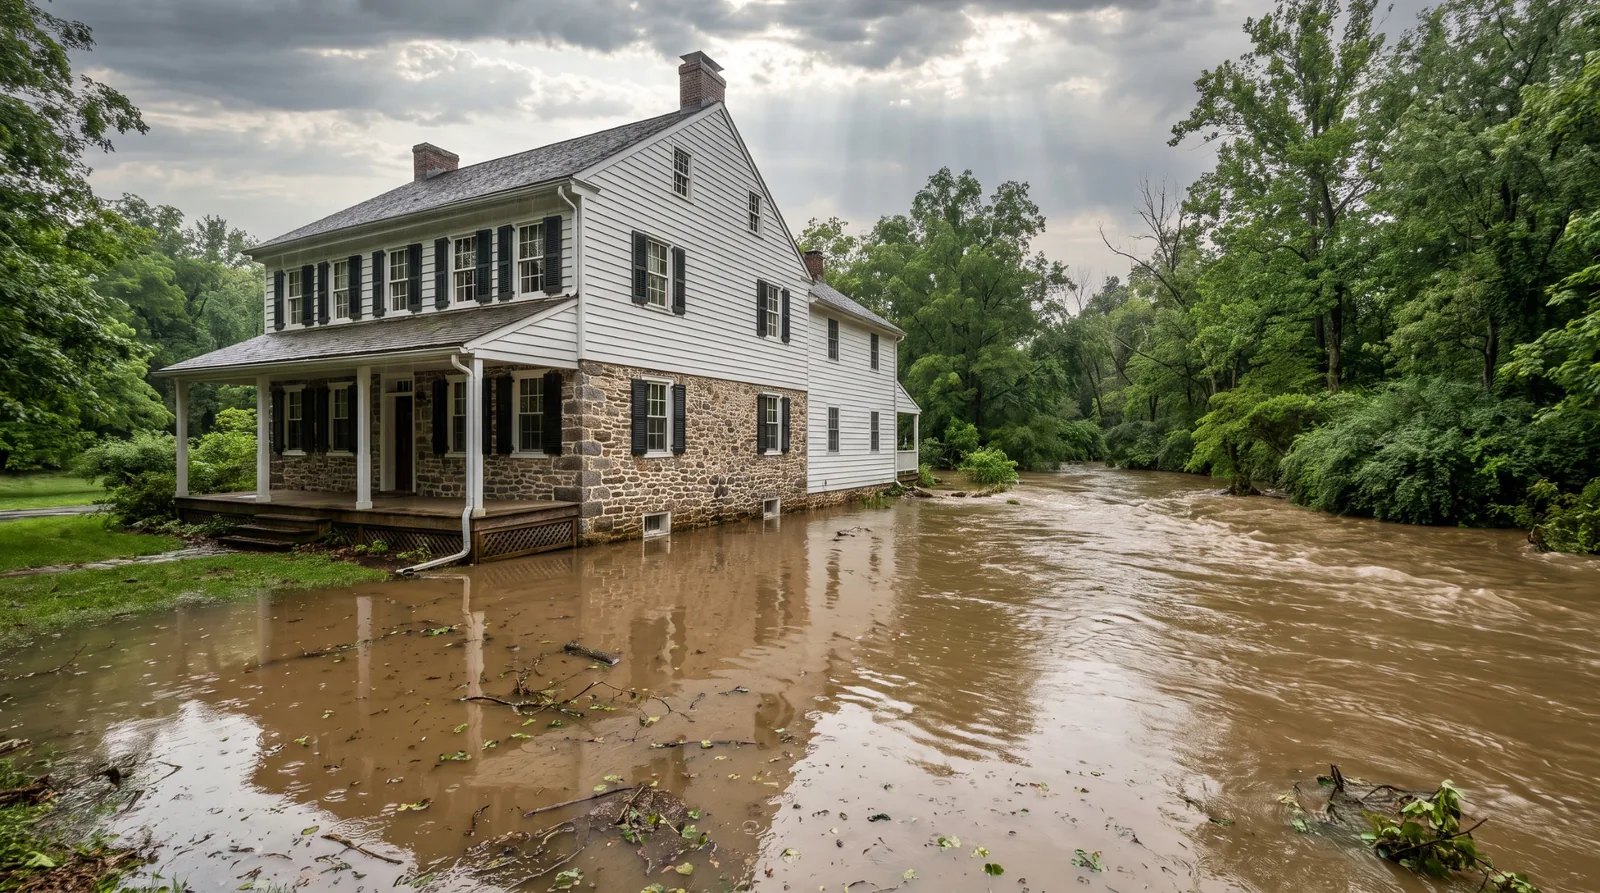 Snowmelt & Storms
 For Families
 Weekends & Getaways
More ways we protect you. Coverage built around real life.
We Shop For You
More than one option.
One honest comparison.
We quote your coverage with Farmers® and, when they fit you better, other insurance companies, lay the options side by side, and help you choose. Then we check it again as the market changes.
1Option #1
Same coverage, compared
Same coverage, compared
2Option #2
Same coverage, compared
Same coverage, compared
Your pick, explained
Reviewed again at renewal
Reviewed again at renewal
Bundling
One agency.
Better together.
Keep your home and auto in one place. We compare options for the pair, handle one review, and bundling may lower what you pay on both.
HHome Policy
Dwelling + liability
Dwelling + liability
AAuto Policy
2 vehicles, full coverage
2 vehicles, full coverage
Bundled and covered
One agency · one review
One agency · one review
Umbrella
One more layer
for what you've built.
An umbrella policy adds liability protection above your home and auto limits. For families with a home, savings and teen drivers, it's often worth a quote. See how it fits with home.
"Our teen just got a license. Are we covered enough?"
Umbrella layer added
Above home + auto limits
Above home + auto limits
$Savings protected
Reviewed every year
Reviewed every year
Annual Review
Your life changes.
Your coverage should too.
New car, remodel, teen driver, new rental. Every year we re-check your coverage and discounts together, free.
"Just added a pool and a new patio. Do we need more coverage?"
Yearly review booked
With Louis
With Louis
Beyond the Minimums
The state minimum
isn't a plan.
Pennsylvania's legal minimums rarely cover a serious crash on US-202 or the Turnpike. We walk you through limits, uninsured motorist coverage and your full or limited tort choice, then size coverage to what you have to protect.
MinimumPennsylvania legal floor
Covers less than most new cars cost
Your plansized to your life
Assets, family & lifestyle accounted for
Landlords
Rental homes,
covered properly.
Own a rental or two around Chester County? We cover the structure, the rent it earns, and the liability many owners miss.
RTwin · West Chester
Dwelling + loss of rent
Dwelling + loss of rent
PRental · Downingtown
Added to the same review
Added to the same review
$Landlord liability
The layer owners forget
The layer owners forget
New Homebuyers
Closing soon?
Let's get it done.
Lender-ready binders, escrow deadlines and proof of coverage, handled. One less thing between you and the keys.
"Closing is Friday. Lender needs proof of insurance!!"
Binder sent to lender
Before closing day
Before closing day
🔑Keys on Friday
Covered from day one
Covered from day one
When It Happens
The day you
actually need us.
A real person who knows your policy, walks you through the claim, and follows up until it's settled. This is what you're actually buying.
!Fender bender · US-202
Everyone's okay
Everyone's okay
Claim started with you
On the phone, step by step
On the phone, step by step
Followed to the finish
Check-ins until it's closed
Check-ins until it's closed
Keep exploring
Why Chester County families work with a local agent. No scripts, no call centers.
We can quote your home and auto with Farmers® and other insurance companies, then lay the options side by side so you can see what each one really covers.
A house, two or three vehicles and a teen driver on the way call for more than Pennsylvania's minimums. We help you set limits that fit what you've built.
We walk you through frozen-pipe, ice-dam and water backup coverage before the first hard freeze, so a claim doesn't come with surprises.
Call and you reach Louis and the same team that set up your policy. We review it with you each year as your family changes.
Talk with Louis →Free policy review
Already insured? Let us check it.
Tell us what you carry now and we’ll check it against the options we can offer. We look for gaps, overlaps and a better fit, then walk you through what we found.
- Share what you have now. Start a quote or give us a call. Have your declarations page handy, or just tell us your current coverage.
- We compare it. Louis and his team check your coverage and price against the options we can offer.
- You decide. We share what we found. No obligation, and nothing changes unless you say so.
We use what you share only to review and quote your coverage, and it is never sold.
Pennsylvania insurance questions. Straight answers.
Why is car insurance going up in Pennsylvania?
Most of it has little to do with your own record. Repair costs, today's vehicle prices, medical bills and busier roads around the Philadelphia suburbs all raise what insurers pay out, and premiums follow.
What you can control: bundling your auto with your home, condo or renters policy, choosing deductibles that fit your savings, your full or limited tort choice, and making sure every discount you may qualify for is applied. And comparing. We look at more than one option for you.
What auto insurance does Pennsylvania require?
Pennsylvania requires liability coverage of at least $15,000 per person and $30,000 per accident for bodily injury, $5,000 for property damage, and $5,000 of first-party medical benefits. Insurers must also offer uninsured and underinsured motorist coverage, and you can only turn it down in writing.
Those are legal floors, not a plan. A serious crash on US-202 or the Turnpike can outrun them quickly, and you could owe the rest. We help you choose limits sized to what you actually have to protect.
What's the difference between full tort and limited tort?
In Pennsylvania you choose your right to sue when you buy a policy. Limited tort costs less, but you generally can't sue for pain and suffering unless the injury is serious or an exception applies, like the other driver being drunk or uninsured. Full tort costs more and keeps your full right to sue for pain and suffering.
Your medical bills are paid by your own first-party benefits either way. It's a real trade-off, so we walk through it with you before you choose.
Does homeowners insurance cover ice dams and frozen pipes?
Often, but it depends on the cause. Sudden water damage from a pipe that bursts in a cold snap, or from an ice dam forcing water under your shingles, is commonly covered. Damage tied to neglect, or to a home left unheated, can be limited or excluded.
Water that backs up through drains or a sewer line usually isn't covered unless you add a water backup endorsement. We'll check what your policy covers before winter, not after.
Do I need flood insurance in Chester County?
It's worth a serious look. A standard homeowners policy does not cover flood. Flood is a separate policy, and we can help you get coverage through the National Flood Insurance Program (NFIP).
The remnants of Hurricane Ida flooded homes across southeastern Pennsylvania in 2021, many of them outside high-risk zones, and creeks like the Brandywine and Chester Creek can rise fast. NFIP policies usually have a 30-day waiting period before coverage starts, so don't wait for the forecast. If your home is in a high-risk flood zone and you have a mortgage, your lender will likely require flood coverage.
How much homeowners insurance do I need?
Enough to rebuild your home, not enough to rebuy it. Your dwelling limit should track the cost to reconstruct your house at today's labor and material prices, which has little to do with what you paid or what a listing site says it's worth.
Under-insuring is the common mistake, and it only shows up at the worst possible moment. We'll run the rebuild numbers with you.
How can I lower my car insurance?
Start by comparing. We can quote your coverage with Farmers® and, when it fits, other insurance companies, instead of handing you one price. Then the usual levers: bundle your auto with your home, condo or renters policy, raise your deductible if you have savings to cover it, drop collision on a car that isn't worth much anymore, and make sure every discount you may qualify for is applied.
A paid-off car, a new driver, a move or a new commute can change what you pay, so we review it with you every year. What doesn't work is quietly cutting your liability limits. That may save a few dollars a month and exposes everything you own.
What is umbrella insurance and do I really need it?
An umbrella policy adds liability protection on top of the limits in your home and auto policies, usually starting at $1 million. If you're found responsible for a serious accident and the claim exceeds your underlying limits, the umbrella picks up from there instead of your savings, your equity or your future wages.
For families with a home, savings and teen drivers, it's often a cost-effective layer. Ask us whether an umbrella makes sense for you.
What's the difference between condo insurance and homeowners insurance?
Your building's master policy generally covers the structure and shared areas. Your condo policy, an HO-6, covers what the master policy doesn't: your interior walls, floors, cabinets and fixtures, your belongings, your personal liability, and assessments the association can charge back to you.
The mistake is assuming the association has it handled. Read the master policy's limits, then insure the gap. We'll read it with you.
Why work with a local agent instead of buying online?
You get a real person who knows your policies and more than one option. We start with Farmers® and can look at other insurance companies when that's the better fit, so a decline or a big renewal increase doesn't have to be the end of the road.
You work with Louis Natelli and his team from your first policy through every renewal, with a free coverage review each year.
Still have questions? Call (914) 419-8000. We'll give you a straight answer.
Ready when you are.
One call covers it all.
Home, auto, life and business coverage from a local agency in West Chester. We compare your options so you don't have to.
Based in West Chester. Serving Pennsylvania families.
The Natelli Agency
📍
Office
Serving West Chester, Chester County and families across Pennsylvania
📞
🕐
Hours
Mon – Fri: 9:00 AM – 5:00 PM Eastern
Sat – Sun: Closed
Sat – Sun: Closed