Home / Business Insurance

West Chester Business Insurance: One local agency for the whole business, shopped for you.

Liability, property, commercial auto and workers' comp for Chester County businesses, plus a plan for Pennsylvania winters. We compare more than one option and walk you through it in plain English.

LocalAgency
More Than OneOption Compared
West ChesterLocal to Chester County
1Local Agency For It All
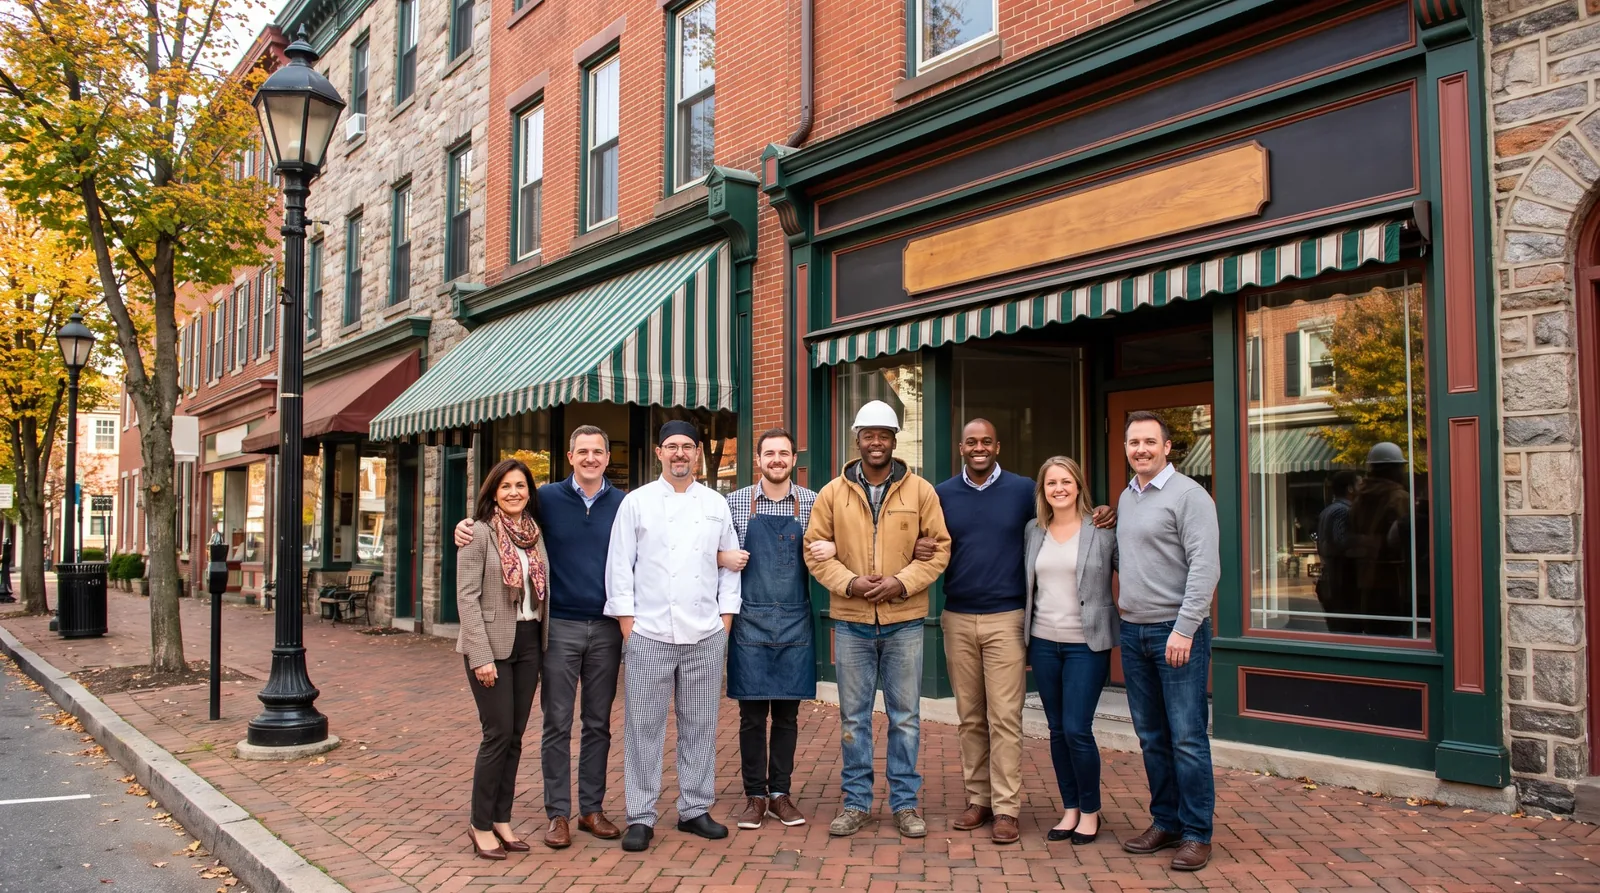
A local business team standing outside their storefront
The Quick Answer

Most West Chester and Chester County small businesses start with a Business Owners Policy (BOP), which bundles general liability, commercial property and business income, then add commercial auto if anyone drives for work. Two gaps catch owners often: personal auto policies typically exclude business use, and homeowners policies largely exclude a home-based business. Pennsylvania requires most employers with employees to carry workers' compensation, so your first hire is a coverage moment too. Winter is the big property risk here: nor'easters, ice dams, frozen pipes and falling trees. Flood is excluded from most business property coverage, and the remnants of Hurricane Ida caused serious flooding across southeastern Pennsylvania in 2021. Professional liability, cyber, EPLI and a commercial umbrella round out the program as needed. The Natelli Agency is a local agency in West Chester, PA that compares more than one option for you. Call (914) 419-8000.

Most small firms
A BOP, plus what your work adds
Pennsylvania risk
Winter storms, frozen pipes, fallen trees
PA workers' comp
Required for most employers with employees
Call first
(914) 419-8000
West Chester Business Insurance, The Short Version

Good business insurance starts with what you do. Then we shop it.

A consultant working from a spare bedroom in Malvern, a shop or restaurant in downtown West Chester, a remodeling crew running jobs from Exton to Kennett Square, a family that rents out a couple of twins: each one needs something different, and none of them needs the whole catalog. Most small businesses start with a Business Owners Policy, which packages general liability, commercial property and business income. From there, we add what your work actually calls for, like commercial auto if anyone drives for work.

We're a local agency, and we don't stop at one quote. We compare your coverage with Farmers® and other insurance companies, lay the options side by side, and walk you through them in plain English. Louis Natelli and his team are based in West Chester, and we work with business owners across Chester County and the Philadelphia suburbs.

Two things shape the conversation in southeastern Pennsylvania. The first is weather. Nor'easters, winter storms and heavy summer storms take a toll on roofs, signs and storefronts. Ice dams and frozen pipes can force a business to close for repairs, and falling trees come down on buildings and parked vehicles. Flood is its own question: the remnants of Hurricane Ida caused serious flooding across southeastern Pennsylvania in 2021, and most business property policies exclude flood. Check your property limits, your deductible and your business income period before winter.

The second is workers' comp. Pennsylvania requires most employers with employees to carry workers' compensation. If you have staff, or you're about to hire, it belongs in the plan from day one. We walk through it below. Nothing on this page is legal advice.
What a business actually needs. In the order it matters.

Start with the package, then add what your work demands: who you employ, what you drive, the data you hold and what a Pennsylvania winter could do to the building.

Start here
BOP

Business Owners Policy

Bundles general liability, commercial property and business income into one package built for small businesses. It often costs less than buying the pieces separately, and for many West Chester offices and shops it's the core of the program.

Core
Liability

General Liability

The customer who slips in your shop, the damage you cause at a client's site, the advertising injury claim. It helps pay defense costs as well as settlements, and it's what your landlord, general contractor or clients will want a certificate for.

Core
Property

Commercial Property

Your building or leasehold improvements, furniture, equipment and inventory. Winter storms, ice dams, frozen pipes and falling trees are real risks in Chester County, so check your limits and your deductible before the first hard freeze.

Core
Reopen

Business Income

Property coverage repairs the building. This helps pay your rent, payroll and lost profit while that happens. Set the restoration period to a realistic timeline, because repairs after a major storm can take longer than you'd expect.

PA rule
Required*

Workers' Compensation

Pennsylvania requires most employers with employees to carry it. It helps pay medical bills and part of lost wages after a work injury. *Think your business is an exception? Ask us first. General contractors usually want proof before you start.

Drive for work
Auto

Commercial Auto

Personal auto policies typically exclude most business use. Vehicles owned by the business need commercial auto, whether it's one car or a few trucks. If staff drive their own cars on your errands, ask about hired and non-owned coverage.

Ask us
E&O

Professional Liability

General liability doesn't cover a mistake in the professional services you provide. If clients pay you for expertise and an error could cost them money, this is the coverage that responds, and your contracts may require it.

Customer data
Cyber

Cyber Liability

A data breach can mean forensic work, notifying customers, legal help and lost income while systems are down. If you take cards or keep customer records, it's worth a look. Coverage varies, so we'll go through it with you.

Your team
EPLI

Employment Practices Liability

Responds to claims like wrongful termination, discrimination and harassment, which can come up in any business with staff. It's worth a conversation once you have even a few employees.

Extra limits
Umbrella

Commercial Umbrella

Sits on top of your general liability, commercial auto and employer's liability limits and adds another layer when a serious claim runs past them. Common when contracts call for higher limits.

Not covered
Home Office

A Business On Your Homeowners Policy

Business property in the house usually has a small limit, and business liability is generally excluded. A client who trips on your front step may not be a covered claim. An endorsement or a small business policy often fixes it.

Not covered
Flood

Flood On A Business Policy

Flood is excluded from most business property coverage, and Ida's remnants caused serious flooding across southeastern Pennsylvania in 2021. Separate flood coverage is available, and NFIP policies usually have a 30-day waiting period, so don't wait for the forecast.

Not sure what your business needs?

Fifteen minutes on what you do, who works for you, what you own and what you drive. We'll tell you what matters, what you can skip, and then compare more than one option. Free, no pressure.

Covering Your Team

Pennsylvania workers' comp, in plain English.

If you have employees, or you're about to hire, this is worth reading. It's general information, not legal advice, and whether any exception applies to your business is a question to ask us directly.

The rule, and when it starts

Pennsylvania requires most employers with employees to carry workers' compensation. If you have staff, plan on carrying it, and line it up before your first hire's first day rather than after. If you think your business might fall outside the rule, ask us before you assume it does.

What the policy actually does

Workers' comp helps pay medical bills and part of lost wages when an employee is hurt on the job. The policy also typically includes employer's liability, which helps if you're sued over a workplace injury. What you pay is driven largely by your payroll and the kind of work your people do, so the more accurately you describe both, the more accurate the quote.

Contractors, subs and the paperwork

General contractors and property managers often ask for proof of workers' comp, on a certificate of insurance, before you set foot on a job. If you hire subcontractors, ask them for their certificates too. Once you have staff, employment practices liability (EPLI) is worth a conversation as well. On employment-law questions, talk to an employment attorney. We handle the insurance.

Before the first nor'easter, check the building.

Ice dams, frozen pipes, a fallen tree and a long closure for repairs. Make sure your property limits, your deductible and your business income period are where they should be before winter weather arrives. Free review.

Whatever you built. Here's where the differences bite.

The right program depends on what you do, not how big you are. These are the situations that change the conversation for Chester County business owners.

Home-based & solo operators

Consultants, bookkeepers, designers and online sellers working from a spare room in West Chester or Malvern. Your homeowners policy wasn't built for your business. An endorsement or a small business policy usually fixes it, and we'll tell you honestly which one you need.

Shops, restaurants & offices

Downtown West Chester storefronts, restaurants and offices usually sign a lease that names the liability limits and the certificate wording. Fixtures, inventory and kitchen equipment need property limits that match, and a frozen pipe over a winter weekend can close your doors for days.

Owners with employees

Your first hire brings Pennsylvania's workers' comp requirement, and EPLI becomes worth a conversation. We'll set it up in plain English before your new hire's first day, and explain what each piece does for you.

Rental property owners

A twin, a row home or a student rental near West Chester University. Rentals like these are usually written on a landlord (dwelling) policy, often with an umbrella over the whole portfolio. See our landlord insurance page.

Contractors & trades

Jobs from Exton to Kennett Square. General contractors and property managers set the requirements: limits, additional insured wording, and proof of workers' comp before you start. We help you meet them and get certificates out quickly.

Businesses with vehicles

A company car, a service van or a few trucks on US-202, PA-100 and West Chester Pike. Personal auto typically excludes most business use, so business vehicles need commercial auto. Staff using their own cars? Ask about hired and non-owned.

Need a certificate of insurance?

Landlord, general contractor, property manager or client waiting on one? Send us the request and the contract language, and we'll work to turn it around quickly with the right additional insured wording.

Business insurance in West Chester. And across Chester County.

We're based in West Chester and work with business owners across Chester County and the Philadelphia suburbs, from West Chester Pike and US-202 out to US-30 and the Pennsylvania Turnpike. Tell us where you operate.

Jump to a topic. Or the coverage behind your life.

Skip to the part of this page you need, or see the personal coverage we write for business owners and their families.

Personal coverage

Pennsylvania business insurance questions. Straight answers.

Do I need workers' compensation insurance in Pennsylvania?

Most likely, if you have employees. Pennsylvania requires most employers with employees to carry workers' compensation.

If you think your business might be an exception, ask us before you assume it is. General contractors and property managers also commonly ask for proof of coverage before you start a job. This is general information, not legal advice.

What does workers' comp actually pay for?

Workers' comp helps pay medical bills and part of lost wages when an employee is hurt on the job.

The policy also typically includes employer's liability, which helps if you're sued over a workplace injury. What you pay is driven largely by your payroll and the kind of work your team does, so tell us about both.

I'm hiring my first employee. What changes?

Workers' comp moves onto the list, because Pennsylvania requires most employers with employees to carry it. Set it up before your new hire's first day, not after.

It's also a good time to look at employment practices liability (EPLI), hired and non-owned auto if they'll run errands in their own car, and whether your liability limits still fit. Call us and we'll go through it together.

What is a BOP, and is it enough?

A Business Owners Policy bundles general liability, commercial property and business income into one package built for small businesses, often for less than buying the pieces separately.

For many West Chester offices, shops and restaurants, a BOP is the core of the program. It isn't enough by itself if you give professional advice, hold customer data, have employees, drive for work, or need flood coverage.

Does my personal auto policy cover me driving for work?

Generally not. Personal auto policies typically exclude most business use, like deliveries, hauling tools between job sites or driving clients.

If the vehicle belongs to the business, it needs commercial auto. If employees drive their own cars on your errands, ask about hired and non-owned auto coverage, because their accident on your errand can become your claim.

I run my business from home. Doesn't my homeowners policy cover it?

Mostly no. Homeowners policies usually carry a small limit for business property and generally exclude business liability.

The fix is often simple: an endorsement or a small business policy. We'll tell you honestly which one fits.

What is professional liability, and do I need it?

General liability covers bodily injury and property damage. It doesn't cover a mistake in the professional services you provide.

If clients pay you for expertise or advice, like consulting, design, inspections or bookkeeping, and an error could cost them money, professional liability (errors and omissions) is the coverage that responds. Your contracts may require it. Ask us what's available for your field.

Do I need cyber insurance if I'm not a tech company?

If you hold customer records, take cards, or run your business through email and cloud software, you have cyber exposure.

Cyber liability can help pay for forensic work, customer notification, legal help and the income you lose while systems are down. What it covers varies by policy, so we'll go through it with you.

Do I need employment practices liability (EPLI)?

Once you have employees, it's worth a conversation. EPLI responds to claims like wrongful termination, discrimination and harassment, which can come up in any business with staff.

General liability policies generally don't cover these claims. On employment-law questions, talk to an employment attorney. We handle the insurance.

What does a commercial umbrella do?

A commercial umbrella sits on top of your general liability, commercial auto and employer's liability limits and adds another layer of protection when a serious claim runs past them.

It's common for businesses with vehicles on the road, heavy foot traffic, or contracts that call for higher limits than the underlying policies carry.

What does business income coverage actually pay?

Property coverage repairs the building. Business income helps pay your rent, payroll and lost profit while that happens, after a covered loss.

Set the restoration period to a realistic timeline, because repairs after a major storm can take longer than you'd expect. Flood is excluded from most business property coverage, and the remnants of Hurricane Ida caused serious flooding across southeastern Pennsylvania in 2021, so ask us about flood coverage too.

Does my business policy cover frozen pipes, ice dams or a fallen tree?

Often, when the damage is sudden and accidental, but the details decide what you actually collect.

Damage from a pipe that bursts suddenly is often covered, while damage tied to neglect or a building left unheated can be excluded. Sewer and drain backup usually needs a water backup endorsement. Check your deductible and your business income period before winter, and call us after a storm so we can help you start the claim.

A client or landlord wants a certificate of insurance. What is that?

A certificate of insurance is proof of your coverage. Naming someone as an additional insured extends your liability policy to protect them for work you do for them.

Leases, general contractors, property managers and larger clients ask for them all the time. Send us the request and the contract language, and we'll work to turn it around quickly.

How much does business insurance cost?

It ranges too widely for one honest number. A home-based consultant and a business with a storefront, a crew and three work trucks are very different risks.

What you do, your payroll, your building, your vehicles and your claims history all move the price. We compare more than one option for your business and walk you through the differences. Call us and we'll quote your actual operation.

Why use a local agency for business insurance?

We can quote your business with Farmers® and other insurance companies, so you see more than one option instead of a single policy.

Louis Natelli and his team are based in West Chester, and we stay with you from the first quote through renewals as your business and the insurance market change.

Still have questions? Call (914) 419-8000. We'll give you a straight answer.

Tell us what you built.
We'll tell you what it needs.

What you do, who works for you, what you own and what you drive. We'll build the program around your business, compare more than one option, and tell you which parts you can skip.